John Redwood's Diary
Incisive and topical campaigns and commentary on today's issues and tomorrow's problems. Promoted by John Redwood 152 Grosvenor Road SW1V 3JL

Anyone submitting a comment to this site is giving their permission for it to be published here along with the name and identifiers they have submitted.

The moderator reserves the sole right to decide whether to publish or not.

Surely not another cold spring?


          According to global warming theory we should be getting early springs and warmer winters. The most enthusiastic global warming theorists were busily forecasting the end to snow in the UK winter looking forward to this decade. They said the winters would not be cold enough to kill off unwelcome bugs. They said spring would come a lot earlier owing to the global warming trend.

         The last three years have seen some tough and snow ridden winters here in the UK. This March we have sub zero temperatures, and on Tuesday morning people were still stuck in their cars in the snow near Gatwick airport from the night before.

          Doubtless we will be told this is just more weather, and less climate. We will be told that the long term trend of temperatures is still upwards, despite the apparent hiatus in rising temperatures worldwide for the last 16 years. The fact that our fuel bills are so high, and that it is so perishing cold in March makes global warming theory a difficult sell to many people. Understandably many people are far more worried about keeping warm and how much it is going to cost. Many businesses are worried about whether it is still economic to make things needing lots of energy in the UK, or whether the intention of EU policy makers is to ensure more and more of the high energy using activities take place outside the EU altoegther , where energy is more realistically priced.

How to get more capital projects


          The Uk is short of roadspace, electricity generation capacity, fast broadband, airport capacity, gas storage, deep water port capacity and homes in the right places. Most people agree it would be good to have more of all or most of these. Most people agree it would be good if the building and construction industry had more work, before its underlying capacity to work is reduced more permanently.

          The government is involved in these matters. Businesses and individuals need planning permission to build. They need Building Regulations approval, and  Health and Safety approval. In cases like energy and aviation the government is involved in pricing decisions and special taxes.It does not mean, however, that the government can or should own the assets and build new ones out of taxpayers money.

            There is a lot of money around in pension funds, insurance funds and held by individual savers. The income  returns on this money are now very poor if you try to stay in low risk assets. If you keep it on deposit or place it into “safe” government  bonds the income is small. Many say they would like some new assets safer than shares that would give them a better yield.

           The government should be able to work with the private sector to develop just such instruments to finance the infrastructure projects we need. The cashflows on a popular tollroad like the Dartford Crossing  or from a baseload new electricity power station are good and reasonably reliable. Finance for such projects could be available where the investor agrees to make money available for say 25 years in return for an income of say 5% or so. The bonds could be traded on the market like government bonds, so you could get out long before the repayment date.

             Many of the potential projects are held up. The government is trying to address the delays. More progress is needed to grant the permits, licences and the planning permissions and settle the tariff regimes so more projects can go ahead.  It would be quite possible to have a much larger capital programme largely financed by private money. So far this has proved elusive, as there are so many obstacles in modern UK and EU government that can get in the way.

          The immediate task of providing more cheaper energy is something we have often discussed here. Ministers do need to revisit damaging EU energy policies which are pricing us out of international markets owing to the business bills, and making it very difficult for many people to afford the domestic fuel bills.

Would more public sector capital projects provide the boost to growth?


The Coalition government has some sympathy with the idea that the public sector needs to boost its own capital investment. The Chancellor has made modest increases to the inherited much cut plans. He does not do more, because he says if he undertook to borrow more markets might lose faith in his fiscal management. If markets drove up the cost of state borrowing, that will take demand out of the economy as interest rates generally rise. That not only hits borrowers, but also undermines confidence and knocks business. It would of course offer some offset as savers had more to spend.

I think there is a larger problem with rolling out big public sector capital programmes. So often the projects the public sector chooses fail to raise productivity but instead gives the state large new future liabilities. The state has to maintain and staff the new buildings and pay the often large losses on the trading assets acquired. The UK is not competitive enough. It needs to raise productivity. It needs to have an affordable public sector. The wrong kinds of public “investment” can make these aims more difficult to achieve.

Some might think, for example, that a new library would be a welcome project. The state then has to provide tax revenue to pay all the future running costs of the library for many years, as it will not bring in any revenue. Meanwhile it leaves open the question of how and when will the UK adapt to the new technology of the web and ebooks. Some believe that HS2 is a crucial economic project that can open up business to the North. However the business plans show it will be heavily loss making and struggle to attract enough passengers. It is twentieth century technology, when China is pressing on with maglev, and the US with its digital revolution allowing good communcations from remote locations.

It seems unlikely that the state can come up quickly with a series of projects that could raise productivity in the state sector, thereby boosting growth and helping reduce future costs of state provision. Short of that it is difficult to see how an enhanced public sector capital programme will lift us out of low growth. Japan has tried this for many years, and just ended up with even more massive state debts than we have. Tomorrow we will consider a larger  privately financed capital programme. This has the advantage that the projects need to meet commercial tests, and do not lumber taxpayers with any failures.

How could we expand demand in the UK economy?

In the run up to the Budget there are three main families of  proposals on offer to boost demand and stimulate growth.

There is the public sector led approach. People argue that the state can still borrow very cheaply, thanks to Quantitative Easing. The state should therefore borrow more to finance state investment projects. They argue that building new schools and railway lines would boost output. Capital budgets which were cut substantially by the outgoing Labour government, largely confirmed by the Coalition, should be temporarily restored.

There is the private sector led approach.  People argue there needs to be tax cuts. The private sector has so far experienced a much tougher squeeze than the public sector overall. If people were allowed to keep more of their own money to spend, it would provide a welcome boost to demand. If companies could keep more of their profits,or could generate more profit in the first place thanks to lower tax bills, there could be an enterprise led revival.


There is the bank led approach. If the banks can be mended and the Central Bank can push money into the banking system from Quantitative Easing, then people argue there will be more credit extended. People will be able to afford new homes and new cars and other goods, there will be more demand. Businesses will be able to borrow to invest and expand.

I will provide a critique of each of these over the next few days. As readers of this site will know, I do think the priority is to fix the banks to allow them to finance a more normal recovery. Tax rates that are cutting the revenues should be reduced. Any other tax reductions to boost people’s spending power  which would be welcome has to be matched by reducing wasteful public spending. More capital investment is needed, but should be undertaken mainly by the private sector.

How fast should the UK economy grow?


                 The Office of Budget responsibility and the Bank of England have been famous for getting their forecasts of growth and inflation wrong in recent years. They do so for a common reason.

                They both believe that the UK has a trend rate of growth similar to that before the 2007-8 financial crisis, of more than 2% per annum. They therefore believe that the current level of  output is well below what it should be – there are “missing years” since the crisis hit. As a result they conclude that the economy can be given extra demand through borrowing and printing money  without causing inflationary pressure. The OBR has also believed that there would be a “normal” cyclical recovery from the large downturn, to get the economy back to its “trend”.

              So far none of this has come true. Inflation has been obstinately high in the UK, hitting more than 5.2% on one occasion at a time when the Bank said it should be much closer to the 2% target owing to large unused capacity.  Growth is now forecast by the OBR to be only half the level this Parliament of its 2010 forecast, and that is still optimstic by the standards of  other forecasters.

             Two of the main points I argued in the Conservative Economic Policy Review published shortly before the crash were that the Uk reached an unsustainable level of activity based on excess borrowing in 2007, and that its future trend growth rate would be around 1% lower than the post war average. The big figure for future  trend growth would be 1, not 2.  I hope I was not too optimistic.

            The trend rate of growth is lower and is likely to remain lower for two important reasons. The first is demand and output was buoyed  up by a massive extension of credit in both the private and public sectors prior to 2008. The Central  Bank induced crunch makes sustaining the levels of private sector credit impossible, leading to a deflation in the private sector. Few want to return to the excesses of private sector lending and borrowing prior to 2008, though it would be good if a new generation could have access to mortgages and business finance on a sensible scale.

         All political parties agree there is a limit on how much extra debt the public sector should take on.  The outgoing government pledged to halve the deficit between 2010 and 2015. The incoming government first pledged to eliminate the structural deficit over this time period. Both have had to suggest delaying adjustment, but neither say the public sector can or should go on adding to its borrowing at recent rates.

         The second is government raised the proportion of the economy represented by public sector activity to a peak of 50%. The public sector in the UK has a very poor productivity record, so a larger public sector holds back growth which rests on productivity advances. In large parts of the public sector there was no productivity growth in the first decade of this century, whereas manufacturing as a sector has sustained a lively rate of productivity growth. When manufacturing only represents 10% of the economy this has limited impact on our general living standards.

          In subsequent posts I will examine what if anything can be done to raise demand in the economy. I will also look at the productivity issue. We can only get richer on average by working smarter and adopting productivity raising technology. How is it going to be done?
Dr Alan Budd should explain why the OBR has got its forecasts so wrong

Instead of being a critic of the Prime Minister, Dr Budd should tell us why the OBR forecast faster and rising growth from 2010 onwards in each of its forecasts. Why did they have to constantly scale them back? They knew the plans for spending and taxing and did not think they got in the way of good growth. Tomorrow on www.johnredwood.com I will  be offering one of the main reasons the OBR has been so off target. It’s nothing to do with deficit reduction. The OBR in Mr Chote’s letter accept that they took into account Labour’s tax rises and capital project cuts, and the further measures the Coalition took in June 2010, and still came up with forecasts of rapid growth for most of the Parliament. They have subsequently revised these down for reasons unconnected  with the policy.

How to create mass prosperity – book by JP Floru


    Mr Floru sent me a copy of his book for review. His study of  the USA, UK, Chile, Hong Kong, Germany, New Zealand and Singapore demonstrates how free enterprise policies generate more wealth and prosperity for all.

      He favours reducing the proportion of the state in the whole as the economy grows. He believes in slimming oversized states by prrivatisation and deregulation. He feels the private sector needs to be given enough freedom and space to grow, innovate, create jobs.

        His case studies over time and ranging widely geographically show  how a dynamic free enterprise sector to an economy can transform living standards and lifestyles for the better. He agrees that we should always take care of the poor, and make sure competition and  the rule of law allows the wealth and income  to spread widely for the benefit of all.

        Lower tax rates, stable and democratic government, and a climate which favours risk taking and peaceful commerce are important elements for success. So too are free trade and the need to stand up to vested interests. Whilst China has done well growing from great poverty through state sponsored capitalism, Mr Floru thinks they will need to pursue liberty more extensively to catch US living standards sometime.

        It is an interesting book with some good case studies. I wonder if the Chancellor will  pick up any good points from the success of other countries willing to unleash free enterprise to generate prosperity? The USSR, Cuba and other communist states illustrated just how bad state planning proved for both living standards and individual liberty. The great experiment between 1945 and 1990 in Europe showed the planned system in the East was far worse than the mixed system in the West. The Asuian success stories show the power of free enterprise to lift people out of poverty.

Support from Mervyn King and Vince Cable?


      In the last 24 hours the Governor of the Bank of England has declared that the government does need to do more to fix and sell the assets of RBS – reinforcing a view expressed here ever since the crisis first hit.

        Dr Cable has wrritten a long and thoughtful article in the New Statesman. I agree with much of it. He too accepts that the commercial banking  system is not operating in the way we need. He also accepts that his approach of developing state banks cannot do nearly enough quickly enough. There is no substitute for fixing RBS, and that should entail a transfer of  as many of  its risks as possible to the private sector.

   The press have lasered in on Dr Cable’s  question whether   the UK state should borrow more long term to finance infrastructure. I agree we need more infrastructure investment, starting with energy, broadband and roads. However, I think given the state’s balance sheet it is vital this should be wholly or largely fiannced by the private sector. Fix the banks, and use the markets. At current interest rates it could be made to work. Offering longer term infrastructure bonds to private investors could also help them, by delivering a reasonable quality covenant with a higher income than is currently available on government or high grade corporate b onds.

        Indeed, I would save the money being spent on the state banks which will remain too tiny to have much impact, fix RBS, selling as much as possible to the private sector, and let the government  lead a move to launch substantial bond  issues for infrastructure to private sector buyers.  That way we cut public spending a little, cut public sector liabilities massively, and have more capital spending.

Energy has become very difficult


      Recently the government has responded to its consultation on “Renewable heat incentive: providing certainty, improving performance”

      Let me give you a flavour of the prose:

“DECC intends to introduce a degression based approach similar to the regime adopted for the Feed-In tariffs scheme. This will involve tariffs available to new applicants being gradually reduced if uptake of the technologies supported under the RHI is greater than forecast. This will be done by monitoring uptake on a quarterly basis against a series of triggers”

In more normal language, the subsidised prices offered for alternative energy will be cut as the popularity of the chosen technology rises.

They are also  allow biomass energy to qualify for subsidy:


“In order to be eligible for the RHI, biomass installations will be required to demonstrate, either through reporting or sourcing from an approved supplier, that their biomass meets a greenhouse gas lifecycle emissions limit target and (from no later than April 2015) land criteria.”

The complexity and cost of all this means the UK ends up with energy which is too dear. It also means we run the danger of not having enough energy available for future needs. Much of this is driven by EU regulations and directives.

I have posted my contribution to the debate on the new Renewable regulations yesterday in a Commons Committee, now available under Debates on this site.

We don’t want too much inflation

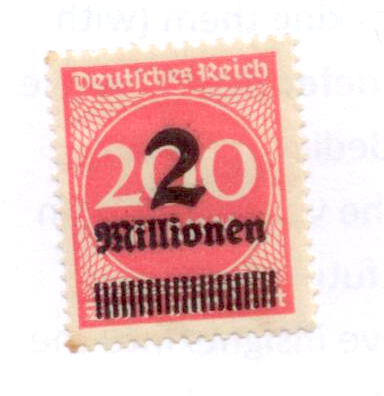
1Sometimes a picture replaces a thousand words. This German 2 million mark stamp  from 1923 in Germany reminds us that even in an advanced western country less than a hundred years ago people lived through a dreadful hyperinflation.  By the peak of the price rises in November 1923 the authorities decided to remove 12 zeros from their currency, creating a new or Rentenmark.  In August 1924 the new Reichsmark replaced 1 trillion of the old marks.

                  The fear of inflation has haunted Germany ever since. It lies behind German current reluctance to print too many Euros to deal with the probpems of state and bank debts in parts of the Eurozone.  Germany knows from bitter experience that if you print too many to get round the problem of managing your debts and deficit you can trigger a collapse of confidence in your currency, a rapid move in to goods, and eventually a hyperinflation.

               Creating a new currency that might be more stable and which people trust is the easy bit of recovering from such a situation. The hard bit is the deep recession or deflation that can follow the bursting of the bubble and the creation of the new stronger currency.

              The Euro area does not today stand on the edge of too rapid an inflation – far from it. The main safeguard against printing too many  Euros  to try to stave off the day when state and bank debts have to be paid is the attitude of Germany herself. That image of the overprinted postage stamp is a timely reminder to Germany and the architects of the Euro that there is no easy way out of excessive state and bank debts or large deficits. If you try too hard to inflate your way out of your debts, you can end up with a worse crisis.